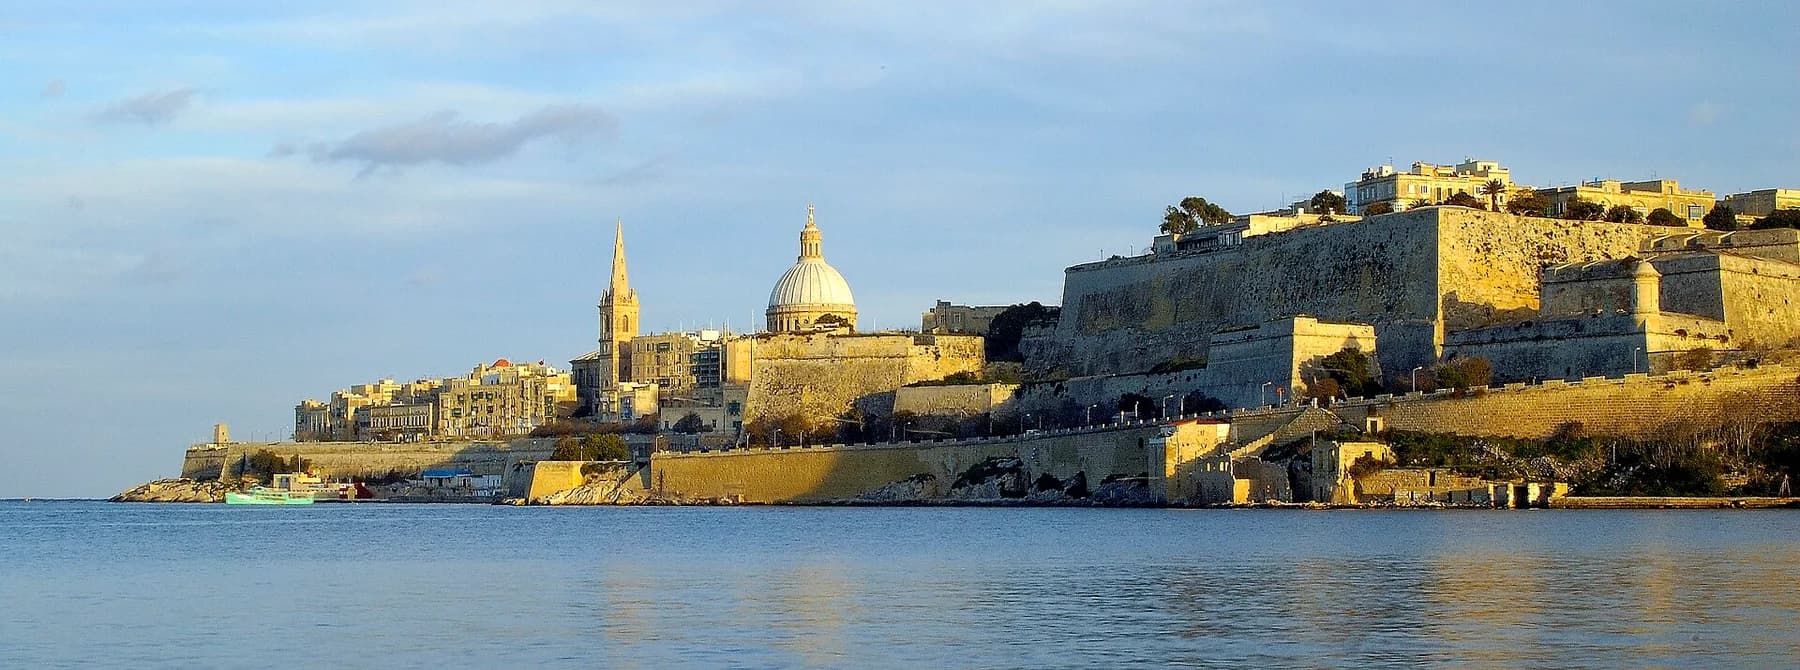
35% standard rate; a 6/7 refund may follow distributions (5% arithmetically). FITWI: optional 15% final taxation, at least 5 years.
Substance
Management and control in Malta; accounting, annual accounts, audit where applicable, annual return. Refunds need cash-flow planning.
Director
Company secretary and registered office included for 12 months. For tax residence: management in Malta.
Best suited to
For businesses able to justify genuine management and activity in Malta. An additional holding company depends on ownership and distribution requirements.
as quoted — Basic administration, renewing the included address and local statutory roles, plus routine register filings and related registry fees. Excluding applicable VAT; accounting provides any required financial information.
Budgeted separately
Share capital where the country requires it, taxes on your activity, bookkeeping, financial statements, tax returns and, where applicable, audits are outside the formation package. Physical offices, operational substance, nominee directors, special licences and additional entities are quoted separately. Bank-application support does not guarantee acceptance.
Potential advantages for your business.
Refund system
The standard corporate tax rate is 35%. After a distribution, shareholders can claim back 6/7 of it, or 5/7 for passive interest and royalties (article 48(4A) ITMA). On trading profits that leaves 5% arithmetically.
A holding company describes a role within an ownership structure, not automatic tax exemption. An additional holding entity, its administration and any refund applications are quoted separately.
As of 09/2026. Benefits depend on activity, actual management, residence and personal circumstances. Company taxation is not the shareholder’s total tax burden.
What this company can offer.
6/7 of the corporate tax goes back to shareholders after distribution
English is an official language, EU location using the euro
Can support operations and shareholdings
Allow for a registered office, company secretary, accounts and annual return. The refund depends on the type of profit and a claim.
When this country fits.
For businesses able to justify genuine management and activity in Malta. An additional holding company depends on ownership and distribution requirements.
Actual management and control, banking, decision records and commercial relationships must support the Maltese activity. A trading and holding structure is an option, not a universal requirement.
The standard rate is 35%. A qualifying 6/7 refund on trading profits can produce a 5% effective Maltese burden, subject to entitlement and procedure. As of 09/2026.
A fiscal unit can consolidate tax calculations for qualifying ownership of at least 95%. It is not an automatic flat-rate election. As of 09/2026.
Eligible entities may elect 15% final taxation under FITWI without refunds, generally with a minimum 5-year commitment. As of 09/2026.
Participation exemption may apply to qualifying holdings. Recipient and income-specific distribution rules still require assessment.
If you move to Malta yourself without being domiciled there, foreign income is taxed only when you bring it to Malta, and foreign capital gains stay exempt (article 4(1) ITA). With EUR 35,000 or more foreign income a minimum tax of EUR 5,000 a year applies (article 56(27) ITA). As of 10/2026.
From context to execution.
1
Review
Ownership, activity, residence and the countries involved.
2
Agreed sequence
Responsibilities, document checklist and open specialist questions.
3
Coordination
Company or residence documents, banking preparation and local professionals within the agreed scope.
4
Handover
Documents and a schedule of ongoing obligations.
Document review, specialist clearance, filing and account or status decisions follow separate processes. Authority and bank decisions cannot be guaranteed.
Ongoing duties.
Accounting, statements, applicable audit requirements, annual returns and tax accounts create ongoing work. Refund-based structures also require cash-flow planning. There is no universal break-even profit.
From a German perspective.
German low-tax testing considers refund rights. Passive income and certain services involving German shareholders may fall within CFC rules; the allocation of refunds and substantive economic activity require review.
Management & permanent establishment
Actual central management and fixed business facilities can create German tax exposure; a foreign registered address is not sufficient.
German nationals meeting all relevant conditions may face extended limited taxation for up to 10 years after the departure year (as of 09/2026). Preferential taxation alone is insufficient.
Tell us your current residence, your business model and your timeframe. In the 15-minute introductory call we establish whether your plans fit what we do.